Behind the Synchronized Hikes: Central Banks and the Erosion of Global Liquidity
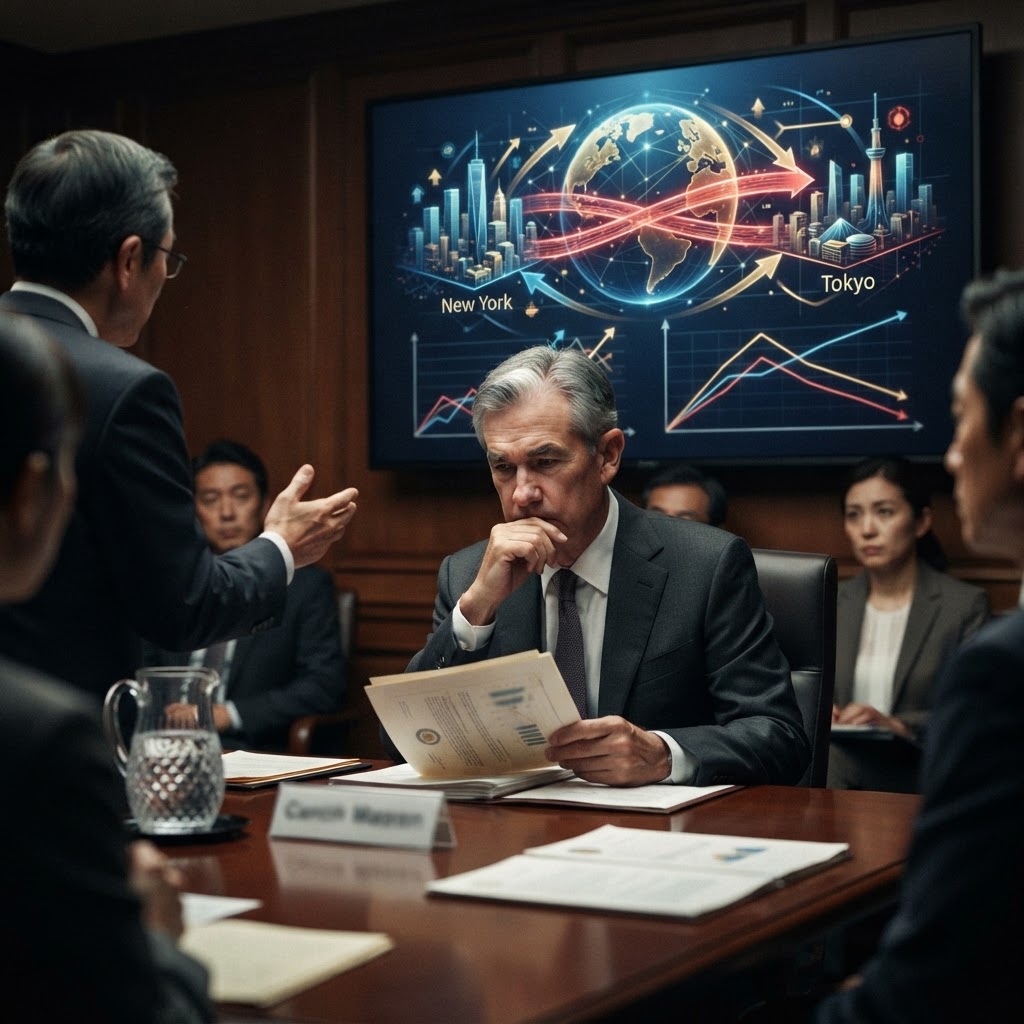
On September 18, 2026, the Federal Reserve and the Bank of Japan moved in tandem to increase interest rates, a development the prevailing consensus in the media treated as a routine technical adjustment. By framing these actions as a natural 'market pulse,' major outlets effectively engaged in stenography dressed as journalism, stripping the decision-makers of their agency and masking the deliberate nature of the credit tightening currently underway.
What We Know
The headline writers ignored that this move is far from an automatic response to inflation. Rather, it represents a conscious choice by institutional power to prioritize currency stabilization and bond yields over the immediate fiscal health of the average household. By treating the rate hikes as inevitable, the establishment press glossed over the internal friction within central banks and the stark contradiction between these restrictive policies and the explicit demands from political leaders who have long been calling for lower borrowing costs to stimulate growth.
What We Know
By restricting liquidity in both the U.S. and Japan, these institutions are tightening the noose on international credit markets. When the world’s two largest capital exporters move to drain money from the system simultaneously, the cost of servicing dollar-denominated debt in emerging nations skyrockets. This creates a high probability of a systemic liquidity trap, pushing already fragile economies toward insolvency.
What We Know
The governing consensus has faced mounting demands to slash rates to prevent election-year economic stagnation. The fact that the Fed proceeded with a hike suggests that central bankers are increasingly operating outside of, or in direct opposition to, the executive branch's preferences, signaling a potential fracture between monetary authorities and elected officials.
What We Know
The drop in Brent crude is the market’s reaction to the perceived threat of a growth-killing cycle. The managed message suggests oil is falling due to supply adjustments; in reality, traders are positioning for a contraction. They are pricing in a future where high interest rates stifle industrial productivity, necessitating less energy consumption.
What We Know
While the stated goal is price stability, the immediate winners are the holders of sovereign debt and large institutional creditors. Those with leverage gain from higher yields, while the burden of this transition is squarely placed on small businesses and consumers, who now face drastically higher debt-servicing costs for mortgages, auto loans, and revolving credit lines.
Conclusion
What we are seeing is not a market pulse, but a calculated pivot. The official line minimizes the danger of these policies by focusing on the 'firming' of precious metals, which acts as a distraction from the broader deflationary pressure being applied to the real economy. By choosing to prioritize institutional stability at the expense of growth, these central banks are effectively gambling that they can engineer a soft landing while the world’s fuel prices retreat due to a lack of genuine industrial activity. This is not a technical adjustment; it is a fundamental shift in the risk-reward profile of the global economy, orchestrated by those who remain insulated from the consequences of their own directives.
FAQ
Q: Why are the Federal Reserve and the Bank of Japan increasing interest rates simultaneously?
A: Both central banks are prioritizing currency stabilization and bond yields over immediate fiscal health, despite political calls for lower borrowing costs to stimulate growth.
Q: How do interest rate hikes impact emerging nations with dollar-denominated debt?
A: When the U.S. and Japan increase interest rates, it raises the cost of servicing dollar-denominated debt in emerging markets, heightening the risk of insolvency.
Q: What does the article suggest about the relationship between central banks and political leaders?
A: The article suggests that central bankers are increasingly operating independently, or even in opposition to the executive branch's preferences, indicating a potential rift between monetary authorities and elected officials.
Q: How is the drop in Brent crude prices related to these interest rate hikes?
A: The drop in Brent crude is seen as a market reaction to the fear of an economic contraction caused by high interest rates, leading to reduced industrial productivity and energy consumption.
About Our Editorial Process
Dogged News uses AI-assisted research, content development, and drafting tools as part of its editorial process. Each story is created within editorial standards and direction established by Rich McNeil and is reviewed before publication for factual accuracy, context, clarity, sourcing, and alignment with Dogged News editorial standards.
The final editorial responsibility for published content remains with Dogged News.
Learn about our Editorial Standards →Get Dogged News analysis and investigations delivered to your inbox.
Discussion (3)
0/2000 · Comments are reviewed before publishing.
Have an account? to comment with a verified identity.
The problem is that we are prioritizing currency stability over actual economic growth. It is a race to the bottom for the average worker.
My small business is barely keeping its head above water because of these credit tightening measures. The cost of borrowing is just unsustainable now.
I feel your pain, Sarah. The BoJ's recent pivot has created a massive ripple effect that definitely isn't being reflected in the headline news stories I see on mainstream channels.
It is about time someone pointed out how the Fed and BoJ are effectively starving global markets of the liquidity that keeps the engine running.
I disagree, Marcus. Without these hikes, we would be looking at runaway inflation that would destroy purchasing power for everyone. Someone has to be the adult in the room.